

Business Insurance
Business insurance, often arranged as a business pack, brings several covers together under one policy. It protects your premises, contents, stock and income, as well as your liability to others. Cover is tailored to your industry, from fire and storm damage to theft, glass breakage and business interruption. For small and medium businesses, the right pack means an unexpected event is a setback, not the end of the business.
FIRE, STORM AND ACCIDENTAL DAMAGE
Helps cover the cost of repairing or replacing your property, equipment, stock and furniture after a fire, storm or similar event, whether you own or lease your premises.
BUSINESS INTERRUPTION
Covers lost income and ongoing expenses, such as rent and wages, if an insured event stops or slows your trading.
THEFT, MONEY AND GLASS
Covers stolen stock and equipment, cash losses up to set limits, and broken windows, shopfronts and display cabinets.
PUBLIC AND PRODUCTS LIABILITY
Protects your business if a customer or member of the public claims your activities or products caused them injury or property damage.
MACHINERY AND ELECTRONIC BREAKDOWN
Covers sudden breakdown of equipment such as refrigeration, air conditioning, computers and point of sale systems.
GENERAL PROPERTY
Covers portable items like laptops, phones and tools against loss or damage, on or off your premises.
Your protection -
Our priority
Don't let the complexity of insurance get in the way of your peace of mind. Simply fill out the form and one of our expert insurance brokers will contact you to help you find the coverage you need.
Protect What You've Built with Tailored Business Insurance
Kirsty is tenacious and driven in both her professional and personal pursuits. She is a go-getter, consistently inspired by the entrepreneurial spirit of Elon Musk. Outside of work, she enjoys yoga, boxing and jet skiing. She placed third in the world for karate at the age of nine, and now holds a Black Belt First dan in Karate.
What Does Business Insurance Cover?
A business insurance pack lets you choose the sections of cover your business needs and leave out the ones it doesn't. Sections and limits vary between insurers, and some also offer optional cover for flood, goods in transit and employee dishonesty. These are the sections most packs include:
Property Damage and Stock
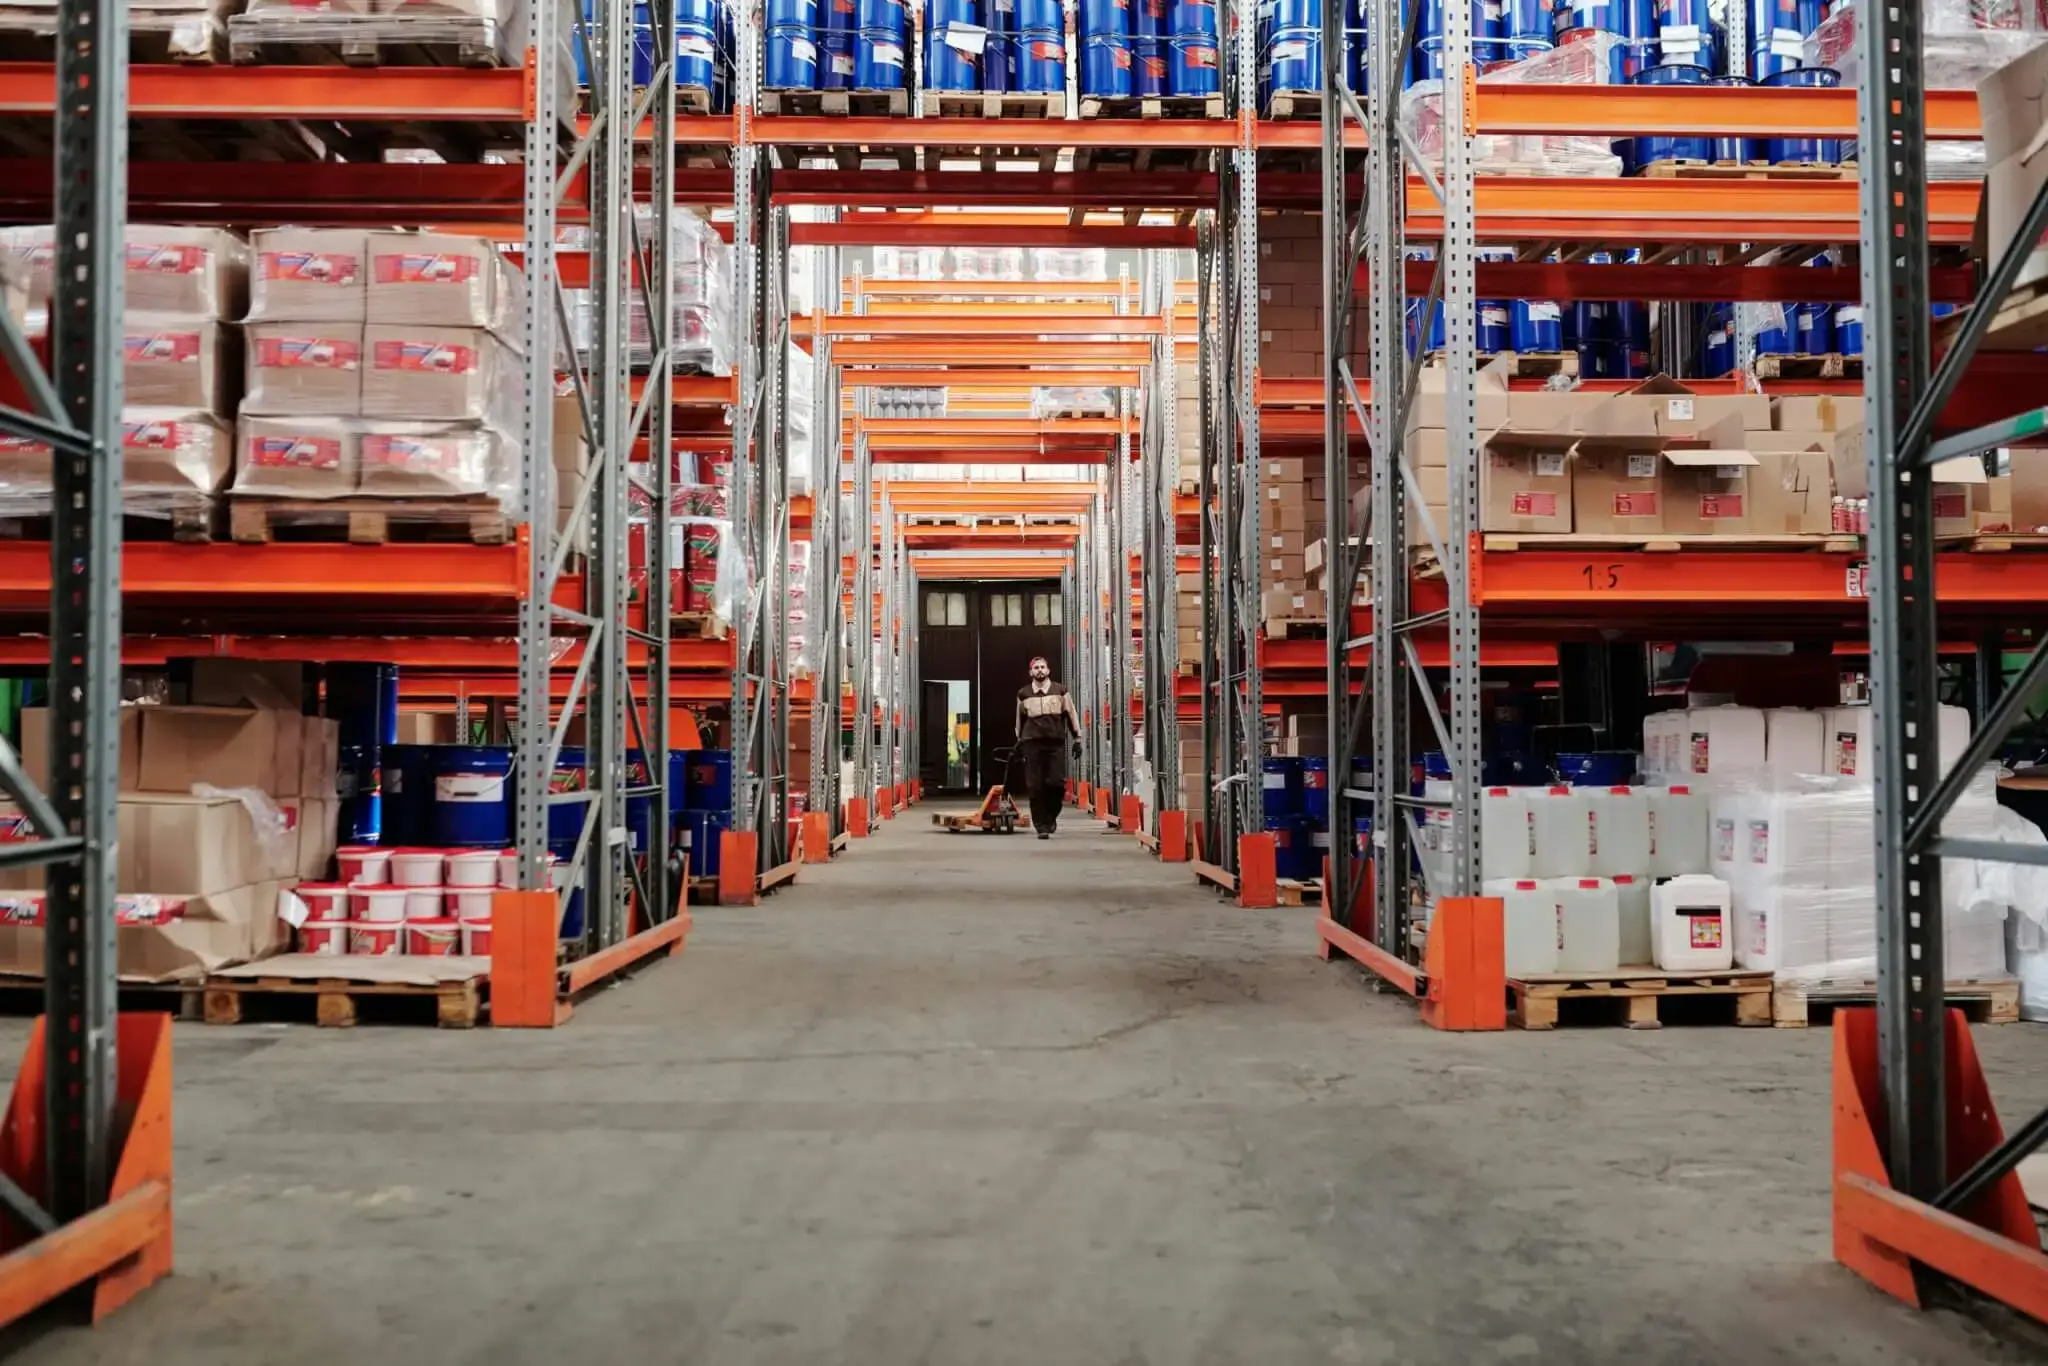
Covers your buildings, contents, fit-out and stock against events such as fire, storm and accidental damage. Stock is insured for its own sum, so set a figure that reflects your peak levels, such as the lead-up to Christmas. Flood cover is not always included as standard. Many insurers can add it for an additional premium, so tell us if your premises are in a flood-prone area.
Business Interruption
Pays ongoing business costs, such as rent and wages, and covers lost income if an insured event like a fire interrupts your trading. It can also contribute to extra costs, such as operating from a temporary location.
Theft, Money and Glass
Covers stock and contents stolen from your premises and damage caused during a break-in. Money cover protects cash up to set limits, and glass cover pays for broken windows, shopfronts and display cabinets.
Public and Products Liability
Covers your legal liability if your business activities or the products you make or sell cause injury, death or property damage to someone else, including associated legal costs.
Machinery Breakdown
Even well-maintained machinery can fail. This section covers repairs after a sudden mechanical or electrical breakdown of equipment such as air conditioning units and refrigeration systems.
Electronic Equipment Breakdown
Covers breakdown of electronic equipment on your premises, from computers and photocopiers to point of sale systems, so your business stays up and running.
General Property
Covers portable items such as laptops, phones and tools against loss or damage, whether they're on your premises or out on the road.
Tax Audit
Covers professional fees, such as accounting costs, if your business is selected for an audit or investigation by a tax authority.
Who Needs Business Insurance?
Any business with premises, stock, equipment or customers should consider business insurance.
- Retail and E-commerce Stock on the shelf, in your storeroom or held at a warehouse or 3PL, plus shopfronts and customers in store
- Hospitality and Food Kitchens, refrigeration, fit-out and diners on the premises
- Trades Tools and materials on the road and liability for work at client sites
- Professional Services Office contents, IT equipment and visitors to your premises
- Beauty and Personal Care Specialist equipment, fit-out and clients receiving treatments
- Fitness and Wellness Gym equipment, fit-out and members using your facilities
- Manufacturing and Wholesale Machinery, raw materials and finished goods moving between sites
- Not-for-Profits and Community Organisations Clubhouses, halls, equipment and members of the public attending events
What Determines the Cost of Business Insurance?
Every business insurance premium is priced individually. Here's what insurers look at.
- Industry What You Do Sets the Baseline Higher risk activities cost more to insure
- Location Where You Trade Matters Flood and bushfire zones carry higher premiums
- Claims History A Clean History Pays Off Past claims shape how insurers price your risk
Real Business Insurance Claims and Case Studies
See how business insurance has helped Australian businesses recover from unexpected damage and breakdowns. These case studies show the real cost of an incident and how the right policy made the difference.
Machinery Breakdown in Food Manufacturing
What happened: A sausage roll conveyor machine suffered a critical electrical failure when the Variable Speed Drive and control board…
Read the story →Water Damage to Café Premises
What happened: A café experienced water damage after an internal water line failed, causing ongoing leaks throughout the premises. The…
Read the story →What a Business Pack Doesn't Replace
A business pack protects your premises, stock, equipment and income, and covers your liability for injury or property damage. Some risks sit outside it and need their own policy. We'll help you work out which of these apply to your business.
- Professional Indemnity Public liability covers injury and property damage. Professional indemnity covers financial loss a client suffers because of your advice or services. Essential for accountants, consultants, designers and other advisers. See Professional Indemnity Insurance.
- Management Liability Covers directors, officers and the company itself for claims such as employment disputes, regulatory investigations and, where the law allows, statutory fines and penalties. See Management Liability Insurance.
- Commercial Motor Vehicles used for business, from a single ute to a delivery fleet, need their own policy. A business pack doesn't cover damage to or caused by your registered vehicles. See Commercial Motor Insurance.
- Cyber Insurance Data breaches, ransomware and business email compromise are generally excluded from business packs. Cyber insurance covers response costs, lost income and your liability to affected customers. See Cyber Insurance.
- Workers Compensation Injuries to your employees are covered by workers compensation, which employers must hold under state and territory law, not by your business pack.
How to Choose the Right Business Insurance Policy
Every industry has different priorities. Here's where to focus for yours:
- Retail and E-commerce Theft and glass cover for stock and shopfronts, plus products liability for the goods you sell. If stock is held at a warehouse or 3PL, make sure that location is declared on the policy.
- Hospitality Machinery breakdown for refrigeration and cooking equipment, and business interruption if a fire or leak forces you to close. See Hospitality Insurance.
- Trades General property cover for tools on the road, and public liability for work at client sites.
- Professional Services Electronic equipment cover for your IT, with professional indemnity and Cyber Insurance alongside your pack.
- Beauty and Personal Care Cover for specialist equipment, and check that the treatments you offer are covered under your liability policy.
- Manufacturing Machinery breakdown and business interruption to protect production. See Manufacturing Insurance.
- Fitness and Wellness Public liability for members using your facilities, and property cover for equipment and fit-out.
- Home-Based Businesses Most standard home insurance policies don't cover business activities, so add business contents and public liability if clients visit or you use specialised equipment.
Business Insights for Australian Businesses
We picked these guides for business owners reviewing their cover.
Business Insurance: Essential Policies You Can’t Ignore to Shield
Have you recently launched a small business, such as a retail store, a tech startup, or a…
Read more →
Liability Insurance Explained What You Need to Know for Any Industry
What You Need to Know for Any Industry Are you a small business owner, or part of…
Read more →
The 2026 Vero SME Insurance Index: What It Means for Your Business
What Australia’s largest annual SME insurance survey reveals about the gap between what businesses believe and what’s actually…
Read more →Frequently Asked Questions
Is business insurance compulsory in Australia?
Most business insurance is optional, but some cover is required by law. Employers must have workers compensation insurance, and third party personal injury (CTP) insurance applies to vehicles your business uses. Public liability may also be a licensing requirement for some occupations in certain states and territories.
What business insurance should I get?
It depends on your industry, location, size and specific risks. A business pack protects your property and income, and many businesses also need Professional Indemnity, Management Liability, Commercial Motor or Cyber Insurance. A broker can help you work out the right mix.
What is a business pack?
A business pack combines several sections of cover, such as property damage, business interruption, theft and public liability, into one policy. You choose the sections your business needs and leave out the ones it doesn't.
What if I run a business from home?
Most standard home insurance policies in Australia don't cover business activities. If clients visit your home or you use specialised equipment, tell your insurer and consider additional cover such as business contents and public liability. Not disclosing your business activities could cause problems if you need to make a claim.
Does business insurance cover flood?
It depends on the policy. Some insurers include flood as standard, many offer it as an optional extra for an additional premium, and a few won't cover high-risk locations at all. Rainwater run-off from a storm is generally covered under the storm section, while flood and storm surge are treated differently by each insurer. We'll confirm what's available and included before you buy.
How much cover do I need?
Your sums insured should reflect the full cost of replacing your property and the income you would lose while you recover. If your cover is too low, an underinsurance clause may reduce what the insurer pays, so review your sums insured at each renewal.
Does business insurance cover injuries to my employees?
No. Work-related injuries to employees are covered by workers compensation insurance, which employers must hold under state and territory law.
Discover our tailored business insurance solutions in Brisbane, Gold Coast, Townsville, Sydney and Melbourne.
Get a Business Insurance Quote Today
Get a Free QuoteLet us lead you to victory.
Why work with Knightsbridge Insurance Group?
At Knightsbridge, we understand the challenges of owning and running a business in-depth. Our dedicated insurance brokers expertly align your business operations and goals with the right policies, shedding light on potential business risks you may not have considered on your own.
We Give to Earn
Evolution is a Process — not a One-Off
Great Minds, Think Differently (not Alike)
Connection Matters
The most important thing in communication is hearing what isn’t said.
Peter Drucker